Inflation Impact on Savings
The Definitive Guide to Purchasing Power Erosion, Monetary Debasement, and Portfolio Immunization
In the sophisticated disciplines of macroeconomic theory and personal wealth management, inflation is universally defined as the persistent, systemic, and compounding increase in the general price level of goods and services within a closed economy over a specific temporal horizon. Conversely, it is most accurately understood not as goods becoming more expensive, but as fiat currency fundamentally losing its underlying value. As the aggregate cost of living scales upward, every standardized unit of currency effectively purchases a fractionally smaller percentage of the same economic utility. For individuals engaged in long-term financial planning, multi-decade capital accumulation, and retirement preparation, inflation operates as an invisible, relentless, and compounding tax on static capital.
Standard retail financial literacy overwhelmingly emphasizes the visceral dangers of high-interest consumer debt or extreme equity market volatility. However, quantitative analysis reveals that the subtle, silent erosion of purchasing power through systemic inflation is mathematically the most pervasive and destructive threat to long-term financial sovereignty. Unmitigated inflationary pressure fundamentally alters the Time Value of Money (TVM), dictating a harsh economic reality: capital deferred for future use will inherently hold substantially less economic utility than capital consumed in the present. Mastering the complex, non-linear mechanisms by which inflation metabolizes accumulated savings is the absolute, non-negotiable prerequisite for engineering a resilient, multi-decade wealth preservation strategy.
1. The Mathematical Mechanics of Purchasing Power Erosion
To accurately quantify the destructive impact of inflation on savings, financial economists rely on the absolute distinction between nominal interest rates and real interest rates. The nominal rate is simply the stated percentage yield provided by a financial institution—for example, a high-yield savings account advertising a 4.5% Annual Percentage Yield (APY) or a corporate bond bearing a 5.0% coupon. The real interest rate, however, is the nominal rate explicitly mathematically adjusted to account for the corrosive effects of macroeconomic inflation. This critical relationship is formalized by the Fisher Equation.
In basic, colloquial finance, the Fisher Equation is often approximated as: Real Interest Rate ≈ Nominal Interest Rate − Inflation Rate. However, for precise, multi-decade capital compounding models, wealth managers utilize the exact geometric formula:
Exact Real Rate of Return Formula:
(1 + Real Rate) = (1 + Nominal Rate) / (1 + Inflation Rate)
Real Rate = [ (1 + Nominal) / (1 + Inflation) ] − 1
When the centralized inflation rate—typically measured by the Consumer Price Index (CPI) or the Personal Consumption Expenditures (PCE) index—exceeds the nominal yield generated on a savings vehicle, the saver experiences a negative real return. If an individual holds capital in a fixed deposit yielding 3.0% annually, but the macroeconomic inflation rate accelerates to 6.0%, the exact real return is mathematically -2.83%. Despite the account balance mathematically increasing in nominal fiat terms, the individual is systematically losing purchasing power. The cost of future liabilities (housing, healthcare, food) is compounding faster than the capital assigned to fund those liabilities.
This dynamic creates a profound and dangerous economic illusion. When retail savers view their monthly commercial bank statements, they observe a nominally larger numeric balance due to accrued interest. This nominal growth triggers a positive psychological response (dopamine release), completely masking the underlying mathematical reality that their stored economic energy is actively bleeding value. Over short temporal durations (e.g., three to six months), this erosion is practically negligible. However, over the multi-decade horizons required for retirement planning, negative real yields can drastically, permanently compromise an individual's standard of living.
2. The "Safe Asset" Paradox and Behavioral Finance
In the realm of behavioral finance, the concept of "risk" is frequently misunderstood by the general public. Retail investors, guided by loss aversion, traditionally define risk strictly as the potential for nominal capital loss—the immediate possibility that an account balance will drop below its initial principal investment value. Driven by this narrow, psychologically flawed definition, risk-averse individuals aggressively hoard capital in highly secure, zero-volatility environments such as checking accounts, basic savings accounts, fixed-term certificates of deposit, or physical cash reserves in a vault.
This cognitive bias gives rise to the "Safe Asset Paradox." By attempting to completely eliminate nominal principal risk, the saver mathematically guarantees their exposure to absolute purchasing power risk. Cash and basic cash equivalents are uniquely and acutely vulnerable to inflationary environments because they possess zero intrinsic growth mechanisms capable of organically outpacing sovereign currency debasement. In a modern macroeconomic regime characterized by permanently expanding monetary supplies (M2 expansion) and rising consumer prices, holding 100% of one's long-term capital in fiat currency is not a "risk-free" strategy; it is a mathematically guaranteed strategy for systemic wealth depletion.
Fiduciary financial planners frequently diagnose this behavioral phenomenon as "reckless caution." While short-term emergency contingency funds (3 to 6 months of baseline survival expenses) must be kept in highly liquid, nominally secure accounts to absorb sudden life shocks, any capital intended for deployment beyond a five-year horizon must be transitioned from a preservation stance to an accumulation stance. Failing to transition excess capital into inflation-hedged risk assets transforms what was intended to be financial security into the slow, mathematical liquidation of lifelong labor.
3. The Mathematics of Long-Term Compounding Decay
To fully grasp the severity of inflation on long-term savings, an investor must learn to apply the principles of compound interest in reverse. Just as invested capital grows exponentially over time, the purchasing power of uninvested capital decays exponentially. Central banks in developed economies typically target a structural inflation rate of approximately 2.0% to 3.0% annually to stimulate consumption (preventing deflationary spirals) and gracefully manage massive sovereign debt burdens.
Using the Rule of 72—a robust heuristic mathematical formula used to estimate the number of years required to double invested capital or, conversely, halve purchasing power at a fixed annual rate—we can project the devastation of long-term inflation. The formula is simply: 72 / Annual Inflation Rate = Years to Halve Purchasing Power.
- At a 2.0% Inflation Rate: 72 / 2 = 36 years. A 30-year-old saver holding cash will see it lose exactly half its value by the time they reach standard retirement age at 66.
- At a 3.0% Inflation Rate: 72 / 3 = 24 years. Purchasing power is halved in less than a generation.
- At a 6.0% Inflation Rate: 72 / 6 = 12 years. During periods of acute macroeconomic distress or supply-chain failure, static wealth is violently destroyed in slightly over a decade.
Consider a newly retired couple holding a $1,000,000 nest egg entirely in uninvested cash under a baseline 3.0% inflation regime. By year 24 of their retirement, that $1,000,000 will only purchase what $500,000 could buy at the start of their retirement journey. If they survive to year 30, the real value has decayed to roughly $411,000. This geometric decay illustrates precisely why retirement planning cannot rely solely on the absolute accumulation of a fixed nominal sum. The target retirement portfolio must be rigorously stress-tested against decades of compounded price increases to ensure the withdrawal rate survives terminal age.
4. Empirical Case Studies: Navigating Inflationary Regimes
Case Study 1: The Conservative Retiree (Nominal Security vs. Real Ruin)
Scenario: Arthur (65) retires with a portfolio of $1,200,000. Terrified of stock market volatility following a recent localized recession, he instructs his broker to liquidate all equities. He moves 100% of his capital into a portfolio of fixed, 10-year government bonds and certificates of deposit (CDs) yielding an average nominal return of 2.5% annually. His initial retirement lifestyle requires $50,000 per year.
The Mechanics of Ruin: For the first five years, inflation averages a mild 2.0%. Arthur is comfortable; his $50,000 withdrawal is adequately covered by the $30,000 in bond yield plus a tiny $20,000 principal drawdown. However, in year six, a structural macroeconomic shift occurs, pushing sustained inflation to 4.5% for the next decade. To maintain his exact same standard of living, Arthur's required withdrawal leaps from $50,000 to over $77,000 by year 15. Because his income is locked at a nominal 2.5%, he is forced to cannibalize massive chunks of his principal every year to cover the escalating cost of property taxes, food, and healthcare. Result: By age 82, Arthur’s portfolio is completely depleted. By choosing absolute nominal safety, he mathematically guaranteed his exposure to inflation-induced insolvency.
Case Study 2: The Millennial Saver (Asset Inflation and the Velocity of Fiat)
Scenario: Maya (28) is a disciplined professional earning $75,000 annually. Her primary financial goal is purchasing a home. She aggressively saves $1,500 every month in a standard commercial checking account yielding 0.5%. The median home price in her target suburb is $400,000, requiring an $80,000 down payment (20%). It takes her exactly 4.5 years to reach her $80,000 cash target.
The Mechanics of Asset Inflation: Maya succeeded in her nominal goal; she saved $80,000. However, during those 4.5 years, the central bank engaged in quantitative easing, inflating the M2 money supply. While general consumer inflation (CPI) rose by 3% annually, asset inflation (real estate) surged by 8% annually due to low mortgage rates and restricted supply. The $400,000 home now costs nearly $590,000. The required 20% down payment has escalated from $80,000 to $118,000. Result: Despite saving diligently, Maya’s purchasing power relative to her target asset collapsed. Because she held her capital in a zero-yield fiat vehicle while the target asset compounded at 8%, the goal mathematically outran her savings velocity.
5. Strategic Asset Allocation Matrix: Immunizing the Portfolio
To systematically immunize long-term savings against the systemic devaluation of currency, capital must be redeployed from static fiat vehicles into asset classes that inherently scale alongside, or aggressively outpace, the general rate of inflation. Modern Portfolio Theory (MPT) categorizes specific asset classes based on their historical inflation beta (correlation).
| Asset Class Category | Inflation Defense Mechanism | Short-Term Volatility Profile | Long-Term Real Yield Expectation |
|---|---|---|---|
| Broad-Market Equities (Index Funds) | Corporate Pricing Power. Companies pass increased material and labor costs directly onto consumers, driving nominal revenue and earnings growth. | High. Highly susceptible to short-term interest rate shocks. | High. Historically generates 5% to 7% real annualized returns above inflation over 20+ year horizons. |
| Real Estate (Physical / REITs) | Hard Asset Scarcity & Rent Indexing. Property values scale with monetary supply; commercial leases are often explicitly tied to CPI metrics. | Moderate. Illiquid in physical form; subject to regional economic cycles. | Moderate-High. Provides compounding equity and inflation-adjusted passive income streams. |
| TIPS (Treasury Inflation-Protected Securities) | Mathematical Indexing. The principal value of the bond is mathematically adjusted upward directly in tandem with official CPI data. | Low. Guaranteed by sovereign government backing. | Zero to Low. Designed to exactly match inflation, preserving purchasing power but generating minimal real wealth expansion. |
| Commodities (Gold, Energy, Agriculture) | Intrinsic Value. Represents the base materials required for economic output, directly reflecting the cost of goods sold. | Extreme. Highly subject to geopolitical shocks and supply chain disruptions. | Zero (Negative after storage costs). Gold produces no yield; it acts purely as a defensive shock absorber during fiat hyperinflation. |
| Long-Duration Fiat Bonds | None. Yields are fixed. | High Duration Risk. Bond prices crash when central banks raise rates to fight inflation. | Negative. The worst performing asset class during acute inflationary cycles. |
6. Calculating and Mitigating the Personal Inflation Rate (PIR)
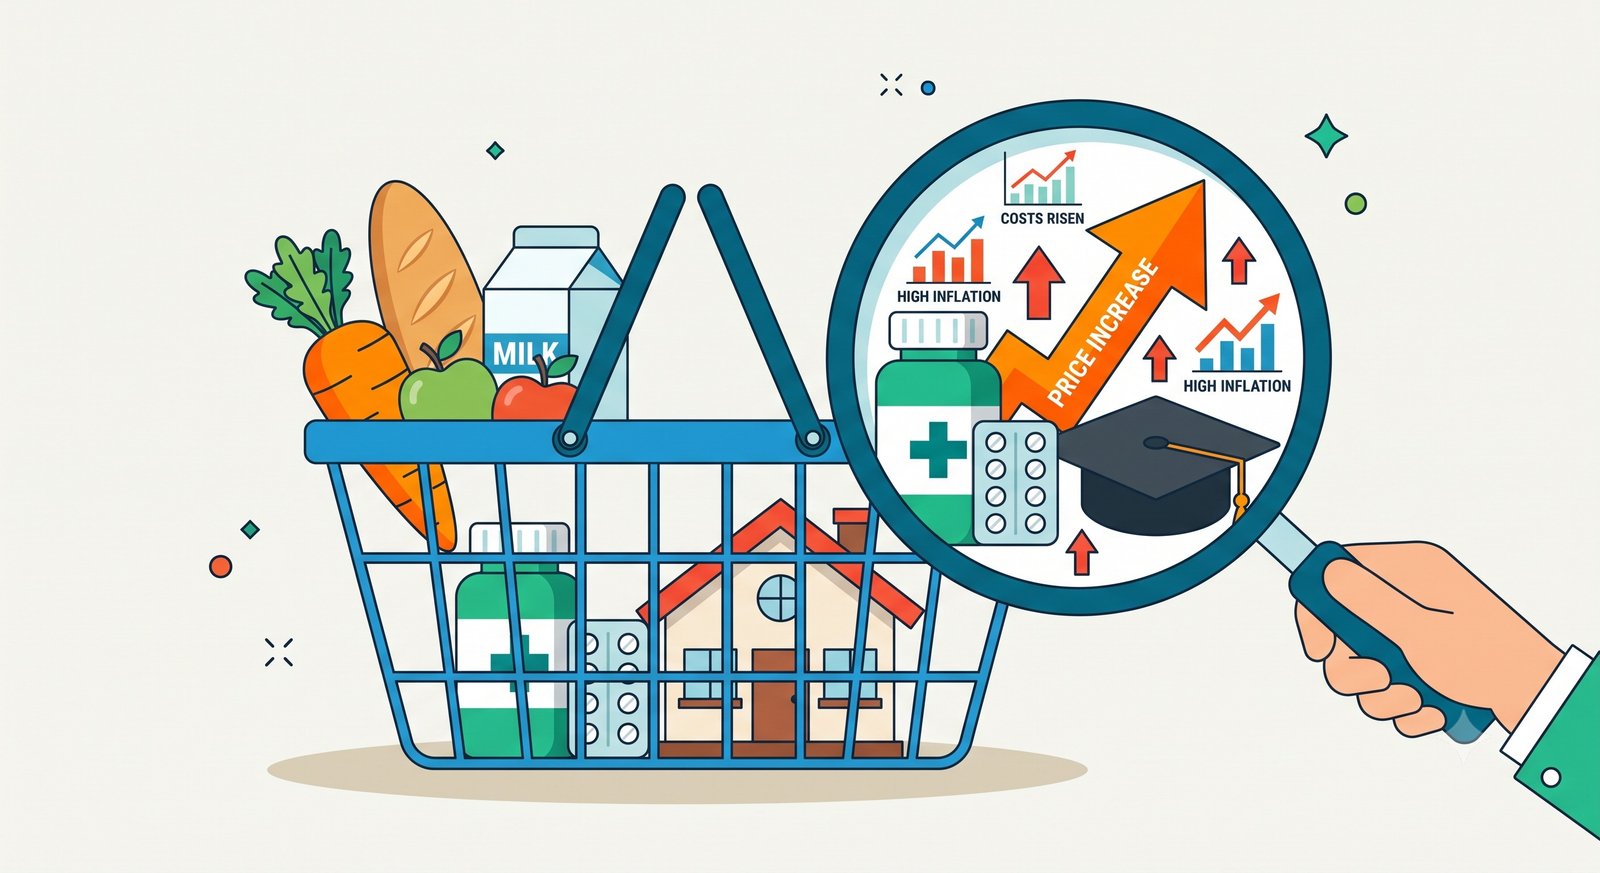
While macroeconomic indicators like the CPI provide a broad overview of national price stability, financial planners urge individuals to operationalize the concept of a Personal Inflation Rate (PIR). The national CPI is calculated using a generalized, standardized basket of goods and services designed to represent the aggregate average metropolitan household. However, an individual's specific consumption and demographic patterns may deviate radically from this national average, resulting in an inflation impact that is uniquely localized and often significantly more severe.
For example, national headline inflation may be reported at a manageable 2.5%, artificially depressed by dropping energy prices and stagnant, deflationary consumer electronics costs. However, a young household primarily consuming localized childcare, specialized medical services, and saving for university tuition—sectors historically experiencing hyper-inflationary cost curves (often 6% to 8% annually)—may experience a localized, effective personal inflation rate closer to 6.5%. Conversely, an elderly retiree who owns their home outright with a fixed-rate mortgage, utilizes public transit, and has heavily subsidized sovereign healthcare is fundamentally insulated from the two largest drivers of cost-of-living increases: housing and fuel.
Therefore, establishing an accurate mathematical baseline for retirement or long-term wealth accumulation requires analyzing one's specific, localized future consumption basket. By auditing past personal spending data across distinct categories (Housing, Transport, Medical, Food) and projecting future lifestyle requirements, an individual can accurately stress-test their portfolio against their true inflation exposure, ensuring they do not rely on generalized national statistics that may severely underestimate the capital required for their survival.
7. Actionable Strategy Guide: Portfolio Immunization Blueprint
Protecting accumulated capital from inflationary erosion requires proactive, systemic structuring. Implement the following fiduciary-grade execution blueprint to transition capital from a vulnerable preservation stance to an inflation-resistant accumulation matrix:
- Step 1: Cap the Fiat Bleed (Right-Size the Emergency Fund). Calculate your absolute Baseline Survival Burn Rate (BSBR). Limit your uninvested cash reserves strictly to 3 to 6 months of this BSBR. Any capital held in fiat checking or basic savings accounts beyond this emergency threshold is suffering unnecessary thermodynamic decay. Route excess capital into the investment pipeline.
- Step 2: Optimize Tier 1 Cash Yields. For the 3 to 6 months of capital that must remain in cash, aggressively optimize the nominal yield. Abandon legacy commercial banks paying 0.01% APY. Transition operational emergency funds into High-Yield Savings Accounts (HYSAs) or Institutional Money Market Funds yielding close to the central bank's baseline interest rate, minimizing the real-yield deficit.
- Step 3: Secure Fixed-Rate Debt Liabilities. Inflation devastates cash savers, but it heavily rewards fixed-rate debtors. If you hold a 30-year fixed-rate mortgage at 3.5%, and inflation surges to 6.0%, the real cost of your debt is actively collapsing. Do not aggressively pay down low-interest, fixed-rate structural debt during high inflationary periods; instead, deploy that surplus capital into equities that scale with the inflation curve. (Note: Variable-rate debt, like credit cards, must be eradicated immediately, as their rates will spike alongside inflation).
- Step 4: Execute Long-Term Equity Accumulation. Deploy capital intended for use beyond a 7-to-10 year horizon into broadly diversified, low-cost global equity index funds (e.g., tracking the S&P 500 or MSCI World). Consistent, automated dollar-cost averaging into productive, cash-flowing corporations is the single most statistically proven mechanism for generating real wealth above the rate of monetary debasement over a lifetime.
- Step 5: Incorporate Real Assets for Terminal Portfolios. For individuals nearing retirement (who cannot tolerate the 30% volatility swings of pure equities), begin migrating a portion of the portfolio into "Hard Assets." This includes purchasing primary real estate, integrating Real Estate Investment Trusts (REITs), or deploying a 5% to 10% portfolio allocation into Treasury Inflation-Protected Securities (TIPS) to guarantee localized purchasing power parity.
8. Frequently Asked Questions (FAQ)
Q: Are I-Bonds better than TIPS for protecting savings from inflation?
Series I Savings Bonds (I-Bonds) and Treasury Inflation-Protected Securities (TIPS) both offer robust sovereign protection against inflation, but serve different tactical roles. I-Bonds are non-marketable, meaning their price never fluctuates; they guarantee your principal while paying a composite rate directly linked to current inflation. However, they are heavily restricted by annual purchase limits (typically $10,000 per entity) and lock up your capital for a minimum of one year. TIPS are marketable securities that can be purchased in massive, unlimited quantities and sold at any time on the secondary market. However, because TIPS trade on the open market, their principal price can fluctuate wildly based on broader interest rate movements. For the average retail saver, I-Bonds are the superior, risk-free inflation hedge for small-to-moderate cash reserves, while TIPS are utilized by institutional portfolios requiring massive capital deployment.
Q: Does inflation increase the stock market's returns?
In nominal terms, yes, but the mechanics are complex. When inflation occurs, the cost of goods sold increases. Corporations respond by raising prices for consumers. This drives higher nominal revenue and higher nominal earnings per share (EPS), which historically pushes stock prices higher. Therefore, over a 20-year horizon, the stock market naturally absorbs and outpaces inflation. However, in the short term (1 to 3 years), acute inflation shocks often crash the stock market. This happens because central banks raise baseline interest rates to fight the inflation, which increases the cost of borrowing for corporations, compressing their immediate profit margins and triggering equity sell-offs. Investors must possess the temporal horizon to endure the short-term shock to capture the long-term inflation adjustment.
Q: Should I buy Gold or Cryptocurrency to protect my cash?
Gold has historically functioned as a store of value over centuries, but it produces zero internal yield (no dividends, no interest). Its price is driven entirely by speculative demand and fear of fiat collapse. While it can preserve purchasing power over a 50-year generational span, its 10-year rolling returns often vastly underperform productive assets like real estate or equities. Cryptocurrencies like Bitcoin are theoretically designed with hard-coded scarcity to resist monetary inflation. However, currently, they behave as highly volatile, speculative risk assets rather than stable inflation hedges. During the massive global inflation spike of 2022, cryptocurrencies crashed alongside tech equities, failing their immediate test as a safe-haven hedge. They may hold speculative portfolio utility, but they should never replace standard productive assets or secure emergency cash.
Q: Why does the bank pay me less interest than the inflation rate?
Commercial banks operate on the principle of Net Interest Margin. They utilize your deposited cash to issue mortgages and commercial loans. To generate a profit, the bank must pay you less for your deposits than they charge borrowers for loans. Furthermore, during periods of quantitative easing or systemic liquidity gluts, banks are awash in excess reserves and have zero financial incentive to offer high yields to attract your capital. Consequently, commercial banking yields are structurally designed to almost always trail the true rate of inflation, guaranteeing that static deposits slowly lose real economic value.
Q: Is deflation better for my savings than inflation?
From a strictly isolated, mathematical perspective, deflation (falling prices) increases the purchasing power of your hoarded cash. If prices drop 5%, your cash is effectively worth 5% more. However, from a macroeconomic perspective, structural deflation is catastrophic. When prices continuously fall, consumers delay purchases (expecting things to be cheaper tomorrow). This crushes corporate revenue, triggering mass layoffs, spiking unemployment, and causing severe economic depressions. Furthermore, deflation makes existing debt functionally more expensive to service. Therefore, while your cash buys more, the likelihood of losing your primary income stream skyrockets. Central banks aggressively fight deflation because a mild, predictable inflation rate (2%) is mathematically necessary to sustain a debt-based, consumptive macroeconomic engine.
See also
- Loading related topics...