Net Worth Calculation
The Definitive Guide to Asset Valuation, Liability Structuring, and Wealth Measurement
In the advanced discipline of personal finance and wealth management, Net Worth serves as the ultimate, unvarnished metric of an economic unit's overall financial health. While budgeting, gross salary, and income generation dictate daily cash flow—functioning similarly to a corporate income statement—net worth represents the personal equivalent of a corporate balance sheet. It provides a static, macroeconomic snapshot of accumulated financial standing at a precise moment in time, brutally stripped of the illusions created by high-income lifestyles or excessive consumer leverage.
Calculating net worth is not merely an exercise in financial vanity or a scorecard for societal comparison; it is a critical, foundational diagnostic tool. It empowers individuals to measure their absolute progress toward financial independence, evaluate the systemic liquidity risk embedded in their current lifestyle, and determine their mathematical capacity to withstand severe economic shocks. Accurately computing this figure requires strict adherence to standardized institutional valuation methodologies, a comprehensive inventory of all financial instruments, and a sober, emotionless assessment of outstanding debt obligations.
The primary failure of retail investors is conflating cash flow with wealth. Earning a substantial income does not automatically generate a high net worth if the Marginal Propensity to Consume (MPC) scales proportionately with that income. True wealth is determined not by the volume of capital that flows through an individual's bank accounts, but by the volume of capital that is captured, retained, and deployed into appreciating, yield-bearing assets over a prolonged temporal horizon.
1. The Fundamental Mathematical Framework
The formula for determining basic net worth is universally defined in accounting standards and mathematically straightforward:
Net Worth = Total Assets − Total Liabilities
Despite the elementary nature of the underlying arithmetic, the complexity and potential for catastrophic error in the calculation arise entirely from how an individual defines, discovers, and assigns monetary value to the variables on either side of the equation.
- Negative Net Worth: When an individual's total liabilities (debts) exceed the aggregate market value of their total assets, they possess a negative net worth. This is a highly common and statistically expected financial state for recent university graduates holding substantial unsecured student loan debt, or young professionals who have recently financed depreciating consumer goods (like luxury vehicles) with minimal down payments. A negative net worth indicates technical insolvency if all debts were called due instantly.
- Positive Net Worth: A positive net worth indicates structural solvency. It means that the individual could, theoretically, liquidate every worldly possession, satisfy all outstanding creditor obligations in full, and still retain a surplus of free capital.
- Liquid Net Worth vs. Total Net Worth: Advanced financial planners differentiate between these metrics. Liquid Net Worth excludes highly illiquid assets like primary residences, private business equity, and locked retirement accounts. It measures only cash and cash-equivalents (like publicly traded stocks) minus all liabilities. This is the truest measure of an individual's ability to survive an immediate, catastrophic macroeconomic shock.
2. Comprehensive Classification and Inventory of Assets
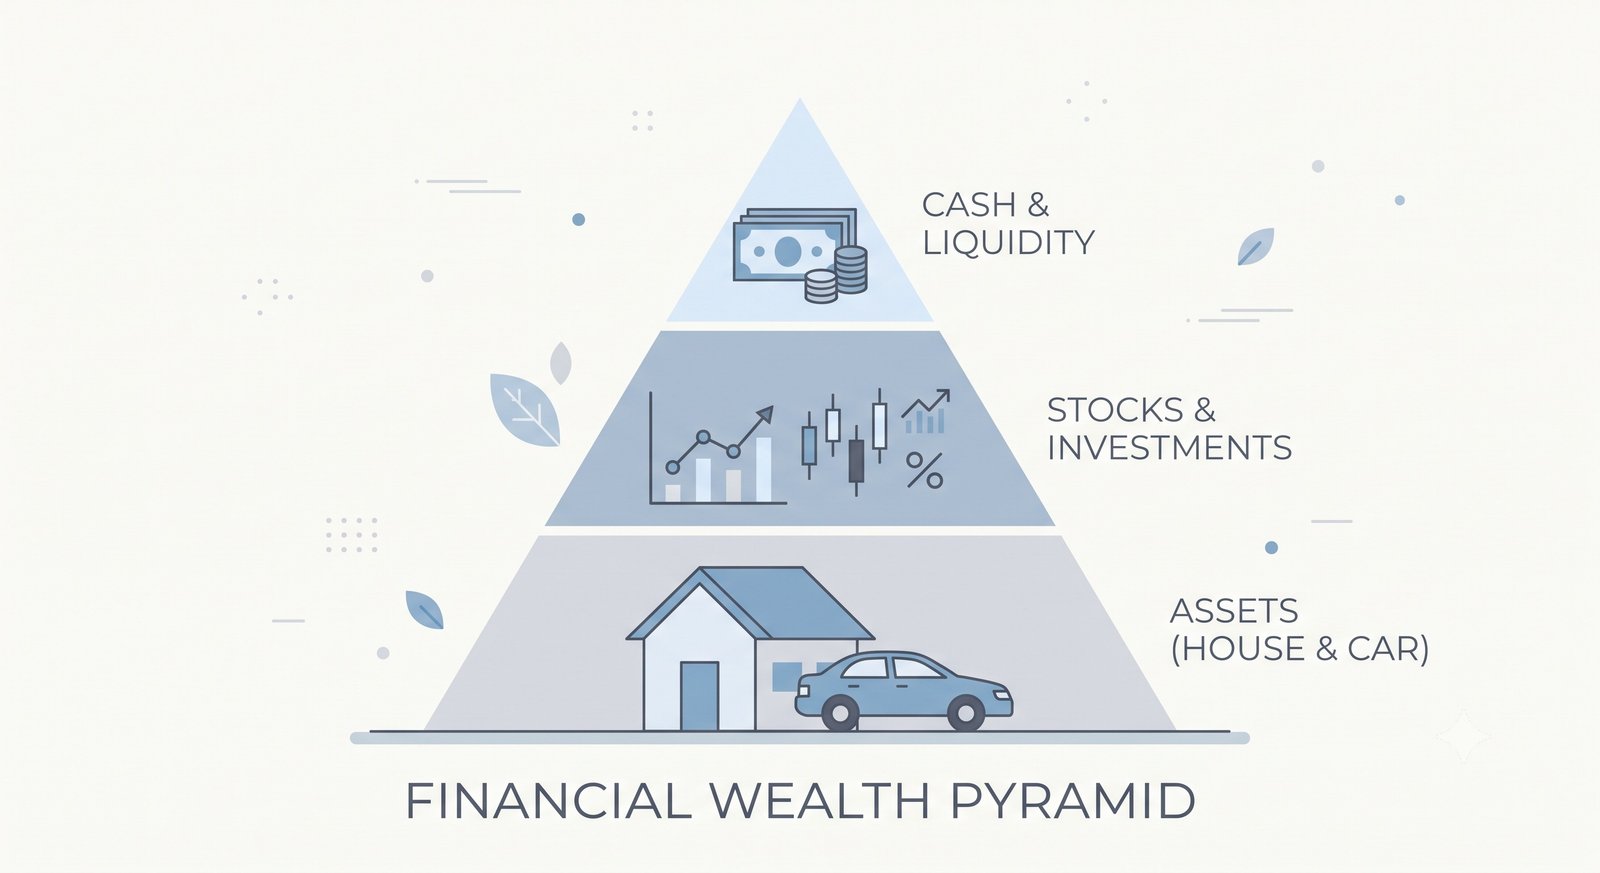
In the context of personal finance, an asset is broadly defined as anything owned that holds positive economic exchange value. However, lumping all assets into a single aggregate number obscures the true health of a balance sheet. Professional wealth managers categorize personal assets into specific tiers based on their liquidity horizons and inherent economic utility.
- Tier 1: Liquid Assets (Cash and Cash Equivalents): These represent capital that can be accessed immediately (T+0 or T+1 settlement) without risking a loss of principal due to market timing. This category includes physical fiat currency, commercial checking accounts, high-yield savings accounts (HYSAs), money market mutual funds, and short-duration Treasury Bills or certificates of deposit (CDs) nearing maturity.
- Tier 2: Marketable Securities (Appreciating Investments): These are paper assets purchased with the explicit intent of generating yield (dividends/interest) or expanding in capital value over time. They are liquid, but subject to price volatility. Examples include publicly traded equities, corporate bonds, mutual funds, Exchange-Traded Funds (ETFs), and accessible brokerage accounts.
- Tier 3: Illiquid Appreciating Assets: These are high-value assets that grow over time but require significant temporal and transactional friction to convert into spendable cash. This includes primary residential real estate, commercial real estate holdings, vested employer stock options subject to lockout periods, and tax-advantaged retirement accounts (such as a 401(k), IRA, or EPF) which carry statutory age restrictions and early withdrawal penalties.
- Tier 4: Depreciating Personal Property: These are tangible items utilized for lifestyle purposes that actively and consistently lose market value over time due to mechanical wear and technological obsolescence. Primary examples include personal vehicles, consumer electronics, furniture, watercraft, and standard jewelry.
There is a fierce, ongoing debate within the fiduciary financial planning community regarding the inclusion of Tier 4 Depreciating Personal Property in net worth calculations. Conservative institutional calculators prefer to exclude vehicles, furniture, and electronics entirely. The rationale is twofold: first, the secondary market for used personal goods is highly illiquid and punitive; second, unless the individual has an immediate, desperate intent to liquidate their daily transportation or dining table, including them artificially inflates the perception of available, deployable wealth. A best practice is to include only assets that you would reasonably sell to fund retirement or survive a multi-year crisis.
3. Identification and Structuring of Liabilities
A liability is any legally binding financial obligation, promissory note, or debt owed to a third-party creditor. Accurate net worth calculation demands a merciless, comprehensive, and objective accounting of all debts, regardless of their interest rates, tax-deductibility, or duration. Intentionally omitting a liability—often driven by psychological avoidance or shame—corrupts the mathematical integrity of the entire financial plan.
- Current (Short-Term) Liabilities: These are obligations expected to be fully settled within a twelve-month accounting period. They represent an immediate drain on cash flow. This category includes outstanding revolving credit card balances, personal unsecured lines of credit, unpaid income or property tax obligations, short-term personal loans, and any past-due medical billing.
- Long-Term (Structural) Liabilities: These represent massive capital debt amortized over multiple years or decades. Primary examples include outstanding mortgage principal balances, automotive financing loans, consolidated student loans, Home Equity Lines of Credit (HELOCs), and long-term commercial business financing secured by a personal guarantee.
- Contingent Liabilities: Often overlooked, these are potential debts that depend on a future event. The most common example is co-signing a loan for a family member. While you may not make the monthly payments, you are legally liable for the total principal if the primary borrower defaults. Conservative net worth assessments track these closely.
Critical Rule of Liability Accounting: When logging liabilities for a net worth statement, only the outstanding principal balance should be deducted. Future unaccrued interest payments—while highly relevant for monthly cash flow budgeting and debt snowball strategies—are not subtracted from the current snapshot of net worth, as the debt could theoretically be settled immediately in a lump sum, bypassing all future interest charges.
| Asset / Liability Class | Valuation Methodology | Net Worth Impact Profile |
|---|---|---|
| Public Equities & ETFs | Mark-to-Market (Closing price on day of calculation) | High volatility; drives long-term positive compounding. |
| Primary Real Estate | Conservative CMA (Current Market Value minus 7% liquidation friction) | Low liquidity; acts as a massive forced savings vehicle. |
| Personal Vehicles | Kelley Blue Book / Wholesale Trade-In Value (Not Retail) | Severe negative drag; depreciates rapidly post-purchase. |
| Mortgage Debt | Exact outstanding principal balance (Excluding future interest) | Fixed drag; diminishes slowly over 15-30 year amortizations. |
| Credit Card Balances | Current statement balance | Toxic drag; high interest rates actively destroy future asset accumulation. |
4. Advanced Valuation Methodologies and Market Dynamics
The most common source of self-deception and error in self-reported net worth stems from improper asset valuation. Professional accounting demands that assets be evaluated using a "Mark-to-Market" approach. This requires estimating exactly what an independent, rational, arms-length buyer would pay for the asset in the open market today, absolutely ignoring what the owner originally paid for it (the "Book Value").
Real estate is notoriously difficult to value accurately without institutional bias. Individuals suffer heavily from the "Endowment Effect," a cognitive bias where humans artificially inflate the value of items simply because they own them. Prudent net worth tracking relies on conservative Comparative Market Analyses (CMAs) generated by local real estate data, completely ignoring speculative "Zestimates." Furthermore, ultra-conservative tracking applies a 6% to 10% reduction to the home's market value to account for the hypothetical real estate broker commissions, transfer taxes, and closing costs that would inevitably be incurred during liquidation.
Similarly, private equity and illiquid business interests present severe valuation challenges. Unlike a share of a publicly traded S&P 500 index fund, which can be liquidated instantly at a universally known market clearing price, private LLCs or sole proprietorships are generally valued using a "Mark-to-Model" approach. This involves taking a conservative multiple of Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA), heavily discounted (often by 20% to 40%) for their lack of market liquidity and reliance on key personnel.
5. Advanced Considerations: Taxes and Liquidity Friction
As an individual's wealth profile becomes more complex and shifts from purely cash-based assets into tax-advantaged vehicles and equities, standard calculations begin to fracture into two distinctly different metrics: Gross Net Worth and Net-of-Tax Net Worth (NTNW). Standard calculators generate a gross figure, which frequently and dangerously overstates an individual's true operational purchasing power by failing to account for embedded, deferred tax liabilities.
Consider an individual holding $1,000,000 in a traditional pre-tax retirement account (such as a US 401(k) or a traditional IRA). That individual does not actually possess $1,000,000 in deployable, spendable capital. Because the capital was invested pre-tax, the sovereign government maintains a permanent, embedded claim on those funds. When the funds are withdrawn in retirement, they will be taxed at the individual's future marginal ordinary income tax rate. If we assume an effective tax drain of 25%, the true liquidatable value of that account is only $750,000. Highly rigorous net worth tracking applies an estimated tax drag (Deferred Tax Liability) to all pre-tax accounts and brokerage accounts with substantial unrealized capital gains.
Net-of-Tax Net Worth = Gross Assets − Liabilities − Estimated Deferred Tax Liabilities
Furthermore, one must rigorously audit Liquidity Risk. Two investors can possess an identical net worth of $2,000,000, yet have vastly different risk profiles. Investor A holds $1.9 million in primary home equity and $100,000 in a checking account. Investor B holds $500,000 in home equity, $1.4 million in diversified liquid index ETFs, and $100,000 in cash. Investor A is classicly "asset rich but cash poor." If a severe medical crisis requires $200,000 in immediate capital, Investor A is trapped; they cannot slice off a bedroom to pay the hospital, and must take out a high-interest home equity loan. Investor B simply liquidates a fraction of their ETF portfolio on a Tuesday afternoon. True wealth measurement must always evaluate the friction required to deploy capital.
6. Empirical Case Studies in Net Worth Calculation
To contextualize these mathematical rules, we will examine two highly detailed, contrasting financial profiles to demonstrate how income and net worth frequently diverge in the real world.
Case Study 1: The High-Income, Negative Net Worth Professional (The HENRY)
Scenario: Dr. Aris (32) is a recently graduated specialized surgeon. He earns a staggering gross salary of $380,000 per year. Societally, he appears extraordinarily wealthy. However, maintaining his expected lifestyle has required massive leverage.
- Assets: Checking Account ($15,000); 401k Retirement Account ($45,000); Luxury Vehicle Trade-In Value ($65,000); High-End Watch Collection ($15,000). Total Assets: $140,000.
- Liabilities: Medical School Student Loans ($310,000); Luxury Vehicle Auto Loan ($75,000 - he is "underwater" on the car); Credit Card Debt from lifestyle spending ($25,000). Total Liabilities: $410,000.
- Calculation: $140,000 (Assets) - $410,000 (Liabilities) = -$270,000 Net Worth.
Analysis: Dr. Aris is a HENRY (High Earner, Not Rich Yet). Despite a top 1% income, his balance sheet is technically insolvent. His high income is entirely consumed by debt service. If he were to lose his ability to perform surgery tomorrow, his $15,000 in liquid cash would sustain his highly leveraged lifestyle for less than a month before catastrophic default.
Case Study 2: The Moderate-Income, High Net Worth Aggregator
Scenario: Sarah (45) is a public school teacher earning a gross salary of $68,000 per year. She lives far below her means, drives a 10-year-old reliable sedan, and has aggressively deployed her surplus capital into appreciating assets over the last 20 years.
- Assets: High-Yield Savings Emergency Fund ($25,000); Diversified Index Fund Brokerage ($180,000); 403(b) Retirement Account ($320,000); Primary Home Current Market Value ($450,000). Note: She correctly excludes her old car from the calculation. Total Assets: $975,000.
- Liabilities: Remaining Mortgage Principal ($160,000); Zero student loans; Zero auto loans; Zero credit card debt. Total Liabilities: $160,000.
- Calculation: $975,000 (Assets) - $160,000 (Liabilities) = $815,000 Net Worth.
Analysis: Despite earning less than 20% of Dr. Aris's salary, Sarah possesses over a million dollars more in true wealth. Because her liabilities are contained strictly to a manageable mortgage, her assets are unencumbered and compounding rapidly. She operates with immense financial security and optionality.
7. Actionable Strategy Guide: Step-by-Step Net Worth Auditing
The true value of calculating net worth lies in longitudinal tracking. Viewing an isolated calculation on a single day is of limited utility; charting the trajectory of your balance sheet across months and years provides unparalleled insight into your systemic financial behaviors. To implement a professional-grade tracking protocol, follow these specific steps:
- Step 1: The Aggregation Phase (Data Gathering)
Establish a dedicated master spreadsheet or utilize a secure institutional financial aggregator (like standard APIs that link bank accounts). Pull the absolute current balance of every checking account, savings account, brokerage portfolio, retirement fund, and HSA on the exact same calendar day. Consistency in the timing of the snapshot prevents cash-flow illusions (e.g., checking before vs. after rent is paid). - Step 2: Conservative Illiquid Asset Valuation
If you own real estate, access local property tax assessments or recent comparative sales data. Do not use the highest possible Zillow estimate. Apply a 7% "liquidation haircut" to the home's value to simulate broker fees. If tracking vehicles, pull the "Trade-In" value from Kelley Blue Book, not the "Private Party" retail value. Enter these figures into your asset column. - Step 3: The Liability Audit
Log into your mortgage servicer, auto loan provider, and every credit card issuer. Record the exact "Outstanding Principal Balance" or "Current Statement Balance" as of that day. Do not include future interest projections. Sum these figures to create your Total Liabilities. - Step 4: Execute the Formula and Analyze the Delta
Subtract liabilities from assets to record your Gross Net Worth. Crucially, compare this number to your previous quarter's calculation. Calculate the "Delta" (the exact dollar amount your net worth grew or shrank). If your net worth increased by $5,000, investigate why: Was it because you paid down $2,000 in debt and saved $1,000, while your investment portfolio grew by $2,000 organically? This analysis is the core of wealth management. - Step 5: Schedule Quarterly Recalibrations
Financial planners generally recommend updating net worth calculations on a strict quarterly or semi-annual basis. Checking it too frequently—such as daily or weekly—exposes the individual to the emotional volatility of the equity markets, potentially triggering panic-induced modifications to an otherwise sound, long-term investment strategy. Set calendar alerts for January 1, April 1, July 1, and October 1 to conduct your audits.
8. Frequently Asked Questions (FAQ)
Q: Should I include the value of my car in my net worth calculation?
It depends on your financial philosophy, but institutional consensus leans toward excluding it unless it holds substantial equity. A vehicle is a rapidly depreciating tool, not a wealth-building asset. If you include a $30,000 car as an asset, your net worth will artificially drop by several hundred dollars every month simply because the car is aging. However, if you have an auto loan against the vehicle, you must include the loan balance in your liabilities. Most planners advise only including a vehicle if it is completely paid off, and even then, heavily discounting its trade-in value.
Q: Is my net worth the same as my liquid net worth?
No. Total Net Worth includes illiquid assets like the equity in your primary home, private business valuations, and locked retirement accounts that carry severe penalties if accessed before age 59½. Liquid Net Worth is a much stricter metric: it only counts cash, cash equivalents, and non-retirement brokerage accounts (stocks/bonds that can be sold on Monday and transferred to your bank by Thursday) minus all your liabilities. Liquid net worth is the true measure of your financial resilience during an immediate crisis.
Q: If the stock market crashes and my net worth drops by 20%, should I change my financial strategy?
Generally, no. This is why tracking net worth daily is psychologically dangerous. A well-constructed balance sheet is designed to withstand macroeconomic volatility. If your net worth drops due to a systemic equity market correction, it represents an unrealized, "paper" loss. As long as your cash flow (budget) is secure and your emergency fund is intact—meaning you are not forced to sell those assets at the bottom—you should maintain your investment strategy and allow the market to recover. Reacting to a paper drop in net worth by panic-selling locks in the loss permanently.
Q: At what age should my net worth transition from negative to positive?
There is no universal statutory age, as it depends heavily on educational debt loads and career trajectories. Medical doctors or advanced degree holders often carry a negative net worth into their early or mid-30s due to massive student loans, despite having excellent future earning potential. Conversely, a tradesperson who entered the workforce debt-free at 18 may possess a positive net worth by 21. The critical objective is not hitting a specific age target, but ensuring the mathematical trajectory (the Delta) of your net worth is consistently moving in a positive direction year over year.
Q: How does marital status affect net worth calculations?
For legally married couples operating under joint finances, net worth is calculated at the household level. You aggregate all joint and individual assets (including separate retirement accounts) and subtract all joint and individual liabilities. If a couple maintains strictly separated finances (often legally structured via a prenuptial agreement), they would calculate individual net worths. However, in community property states or jurisdictions where debts acquired during marriage are considered joint liabilities regardless of whose name is on the paper, an individual calculation can be legally misleading.
See also
- Loading related topics...